Warning for anyone in South Africa who still owes money on their car


South Africans who finance their cars could be left owing money on vehicles they no longer have if their car is stolen or written off, even if they have comprehensive car insurance.
This is according to Naked Insurance, which recently warned motorists about the risks they face when purchasing a car with a payment plan.
Sumarie Greybe, co-founder of Naked, explained that the issue arises because comprehensive insurance covers the insured value of the car (retail, market, agreed or trade-in, depending on the policy) and not the outstanding balance on the finance agreement.
In cases where the car depreciates faster than the loan amount falls, the insurance payout may not be enough to clear the debt.
Credit shortfall cover, otherwise known as gap or top-up cover, can help individuals bridge this gap following a valid claim.
“Imagine making monthly repayments on a car you no longer have. As strange as it sounds, it is easy to assume that comprehensive insurance means you are fully protected, but that is not always the case,” said Greybe.
“If the settlement amount on your finance agreement is higher than the insured value of your car, you remain responsible for the difference.”
The insurer noted that this issue is becoming more prevalent as consumers are becoming more reliant on lengthy finance contracts to keep up with rising car prices.
According to TransUnion’s Q1 2026 Mobility Insights analysis, most loan agreements now extend beyond six years for many motorists.
Contract lengths are rising, and balloon payments are becoming more popular, underscoring an affordability crisis in South Africa’s car market where individuals are more focused on monthly affordability than on the long-term cost of these agreements.
This puts many buyers in a position where they are paying more for the car than it is worth as it continues to depreciate while they are bound by a lengthy contract.
Naked used an example where an individual has a finance settlement amount of R520,000, but their vehicle’s insured retail value is R430,000, leaving them with a R90,000 shortfall.
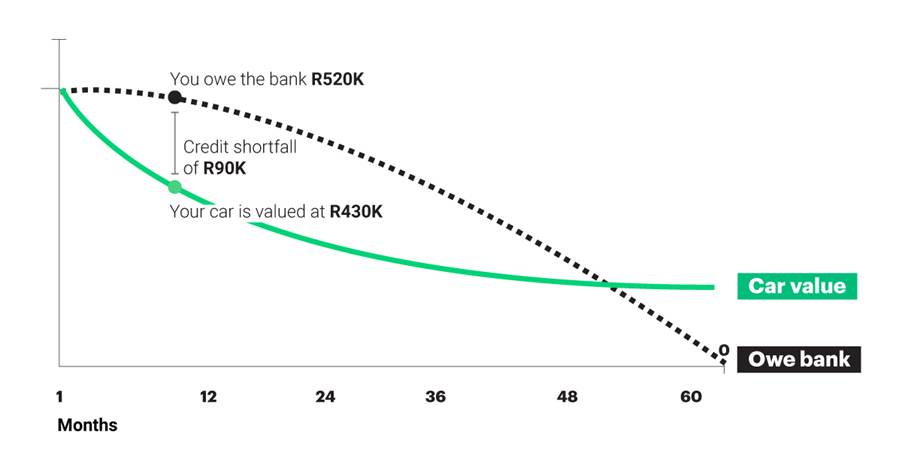
The discrepancy forms because the car’s value and the outstanding loan balance do not fall at the same rate.
Depreciation reduces the car’s value as it gets older with increasing mileage, while a large portion of the money paid towards the loan goes towards the interest rather than the loan itself.
“Customers often tell us they hadn’t considered that they might still owe the bank money after their insurer pays out,” said Damian Colman, Head of Customer Success at Naked.
“To see where you stand, ask your bank what it would cost to settle your loan today and check with your insurance provider what your policy would pay if your car were stolen or written off.”
Colman explained that the risk of a credit shortfall is generally greatest during the first few years of a finance agreement, especially if you opt for a balloon payment as many South Africans do
“If your car is stolen or written off during this period, you could face a difficult choice: buy a cheaper replacement while repaying the shortfall on the original loan, or take on higher monthly repayments to replace the car with one of similar value while also settling the outstanding debt.”
Naked highlighted the circumstances that can commonly lead to a credit shortfall:
- You have a balloon payment – the lump sum due at the end of the repayment period remains part of your outstanding debt.
- You made a small or no deposit – this means you financed more of the car’s purchase price.
- You chose a long repayment term – the longer the loan term, the longer the finance balance may remain above the vehicle’s value.
- You bought a new car – depreciation tends to be steepest during the early years of ownership. A new car may lose around 15% to 20% of its value during its first year and 30% by year two.*
- You have a high interest rate – a greater portion of your instalment goes towards interest rather than reducing the amount borrowed.
- You are early in the loan term – you may not yet have repaid much of the original debt.
“The good news is that shortfall cover is usually available as a small monthly add-on to your car insurance premium, far cheaper than paying off a shortfall on a loan yourself,” said Greybe.

 Loading ...